
FIDUCIARY /fə-dü-shē-er-ē/
Adjective
Involving trust or standard of care whereby one acts in the best interests of another.
“Advisors should always act in a fiduciary capacity.”
Noun
One who acts in a fiduciary capacity.
“A fiduciary should look out for their client’s best interests.”
Aaron( )

First and foremost, Aaron and his firm uphold a fiduciary standard. That means they will always act in your best interests. This is an important distinction, as approximately 90% financial advisors are also registered as brokers and are not held to a fiduciary standard (see The Competition).
Once you find an advisor you can trust, it is important to make sure they are competent. This is where Aaron’s background truly distinguishes itself. Unlike many investment advisors, his focus has always been on research (not sales). He earned a PhD in applied mathematics and worked as a “quant” researcher on Wall Street. While working for two leading investment banks in New York and London, Aaron built and managed global teams that provided investment and risk management services to the firms’ top clients.
Aaron now uses his analytical skills to optimize strategies around tax-efficient income and legacy planning. He has been published and quoted in major newspapers and magazines, including the Wall Street Journal, Financial Times, Barron’s, and New York Times.
Aaron is well respected by his family, friends, colleagues, and clients on both personal and professional levels. He is highly driven and focused on succeeding, but always maintains the highest level of integrity in his endeavors.
Please watch the video below or expand the tabs below to learn more about his track record of achievements in both academia and the investment business.
- Adjunct professor for University of Florida’s Master of Science in Finance (MSF) program
- Executive program for financial accounting and analysis (London Business School)
- PhD in Mathematical Finance (University of Florida)
- Accelerated Master’s Degree in Applied Mathematics (University of Florida)
- Dual undergraduate degrees in mathematics and statistics (University of Florida)
- Minor in actuarial sciences
- Investment banking training program (JPMorgan)
- Inaugural International Baccalaureate class in the Deerfield Beach (FL) school system
- Voracious reader of books on investments – especially those by and about investing greats
- 1996: Worked as a quantitative analyst on William R. Hough’s proprietary trading desk
- 1999: Joined JPMorgan’s highly regarded Risk Management department
- 2001: Transferred to Equity Derivatives Research in London
- 2005: Recruited by Barclays Capital to build their equity research platform
- 2011: Launched Aaron Brask Capital to focus on investment and planning services
- 2018: Started an adjunct professorship for the University of Florida’s Master of Science in Finance (MSF) program
Aaron was born in St. Louis but grew up in South Florida, leading an active lifestyle around tennis, basketball, and surfing. Work first brought him to New York, then London, where he met his wife, Stephanie. After nine years in London and a short sabbatical in France, they moved to South Florida. Aaron and Stephanie are proud parents of Michael and Victoria, but still enjoy tennis, traveling, and other activities when life allows.
AUSTIN

Austin is a U.S. Navy veteran who served as an operations communicator and tactical boat operator, spending the bulk of his five years in the Middle East. He has a B.A. in finance from Florida Atlantic University, which he earned while on the G.I. bill.
Austin previously held positions in the fields of physical therapy and accounting, but his lifelong passion for personal finance and helping others drove him to seek out a career in financial planning.
Austin’s discipline, communication skills, and ethics quickly become apparent to everyone he meets. Moreover, he has come up the curve quickly with his investment and financial planning knowledge. These traits provide a great foundation for a career as a financial planner.
Austin and his wife, Giorgia, enjoy living in Florida. They eat healthy and stay fit by working out and making the most of living near the beach. They also try to spend time with their families, both in the U.S. and Italy.
Jennifer
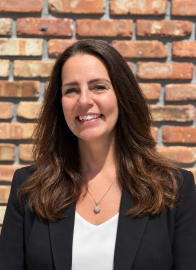
Jennifer is an invaluable member of our team, bringing decades of experience helping organizations operate more effectively. Throughout her career, she has helped businesses improve organization, strengthen client relationships, and streamline day-to-day operations.
Jennifer began her career with American Express and, most recently, served as the Chief Operating Officer of a South Florida electrical and critical power services company. Her broad operational experience and client-focused approach make her an important part of our team.
Jennifer earned her degree in Business Management from Nova Southeastern University. She is also a registered home caregiver in accordance with Palm Beach County’s Home Caregiver Ordinance.
Our Firm
We believe trust and competence are critical ingredients for stewardship of your wealth. The absence of either can pose unnecessary risks by compromising the quality of the advice you receive (e.g., paying more taxes or fees). That is why we structured our firm to serve in a 100% fiduciary capacity.
..INDEPENDENCE HAS ADVANTAGES
 Many investors assume the larger, well-known brokerage houses are the safer option when it comes to managing their wealth. However, the trend is clear; an increasing number of clients (especially those with substantial wealth) are moving to independent investment advisors who serve as fiduciaries. This shift away from brokerage firms is driven by a variety of factors related to conflicts of interest, transparency, fees, and performance.
For those who enjoy cynical humor, Fred Schwed Jr’s book Where Are the Customers’ Yachts? is a great read with plenty of anecdotes about Wall Street firms. This book was written over 75 years ago, but Phil DeMuth and Ben Stein share more candid criticism of financial services firms in their more recent (2013) book The Affluent Investor. Page one sets the tone claiming Wall Street firms are nothing less than “wealth expropriation machines.”
While the next tab (Trust) discusses some of these factors in more detail, the table below highlights some of the key differences between broker-dealers and independent advisors.
6 Benefits of Working with an Independent Advisor.
When working with a broker-dealer, that firm actually holds your assets in-house. Their brokers have access to your funds and assets. The collapse of MF Global highlights the potential risks broker-dealer clients face.
Independent firms hold client assets with third-party custodians (e.g., Charles Schwab or Fidelity). This model creates a system of checks and balances. The independent advisor has discretion to buy/sell securities on behalf of clients but cannot use or transfer monies outside of clients’ accounts.
Brokers are only held to a suitability standard. In particular, they can sell investments and banking products to their clients even when they know of better options. Registered investments advisors (RIAs) uphold a fiduciary standard. That means RIAs must place their clients’ interests ahead of their own.
However, it is important to understand that most advisors (approximately 90%) are dually registered as brokers. While they may market themselves as fiduciaries, their engagement documentation will likely open the door to them serving as a broker. Of course, this language may be buried within a large document or in the fine print.
Broker-dealers often engage in an opaque web of revenue sharing, commissions, and fee arrangements with internal and external affiliates (e.g., fund companies and trading desks). This creates material conflicts of interest; they may be inclined to allocate their wealth management clients’ assets to products based on their kickbacks rather than the merits of the investments.
Independence helps avoid conflicting incentives and temptations to exploit clients. We believe the revenue-sharing agreements many brokerage firms use to receive kickbacks from mutual funds serve as one of the most blatant and common examples.
In particular, it is common for us to encounter brokers and their firms allocating clients’ significant parts of their portfolios to funds with higher fees and poor performance records. In almost all of these cases, we can find the language within the firms’ disclosure documents highlighting how the funds kickback some of their fees to the broker or brokerage firm. This article from Barron’s describes this phenomenon, and highlights some of the big-bank firms that engage in this activity.
Many brokers focus on transactions to generate commissions. While this obviously creates conflicts of interests with clients, a more dangerous aspect of this model is perhaps its piecemeal nature. A comprehensive financial plan should not be based on a series of flavor-of-the-day transactions. This approach is typically very inefficient from both tax and planning perspectives.
We believe genuine advice and robust planning are critical for optimizing one’s financial planning and investments (e.g., retirement). That is why establishing goals and monitoring performance toward those goals are critical elements of our investment process. This helps us deliver peace of mind so our clients can take comfort knowing we manage their affairs with the care and expertise they deserve.
While the nature of the broker model is clearly conflicted, the primary constraints on business strategy often boil down to legality and liability. A quick search of the Financial Industry Regulatory Authority (FINRA) arbitration and mediation filings can illustrate the frequency and magnitude of issues clients have with these types of investment firms.
As a fiduciary advisor, independent investment advisors must maintain a code of ethics that sets forth their standards of business conduct. Taking this a step further in an effort to facilitate the highest degree of transparency, we like to formulate investment policy statements dictating guidelines for the investment strategies and types of investments used with each client. This makes our financial planning and investment process fully transparent so our clients can enjoy more peace of mind.
Brokers often operate on a minimal-disclosure basis with fees explained in small print. After years of seeing portfolios managed by brokerage firms, it is still surprising that many (probably most) prospects we meet are unaware of the magnitude of investment-related fees and how they are levied. Moreover, few brokers compare their performance to standard benchmarks or indices.
Our advisory fees and performance are fully transparent. Charles Schwab provides monthly statements highlighting performance and depicting our quarterly fees in the months they are deducted (Jan/Apr/Jul/Oct). Additionally, Schwab generates separate invoices detailing how they calculate our fees.
Each of our client’s financial plans highlights the fees charged by the investment funds (a.k.a., expense ratios) we use in their portfolios (i.e., ETFs and mutual funds). However, it is worth noting that we lean toward lower-cost index funds for the bulk of our client portfolios.
TRUST
People don’t care how much you know until they know how much you care.– Theodore Roosevelt

Aaron Brask Capital is an independent investment advisor. Being independent means we do not favor any particular firm’s products or services. Being an independent investment advisor (i.e., not a broker) means we always uphold a fiduciary standard. We do not just work with our clients; we work for our clients.
To put this into context, consider the seemingly endless array of labels for financial professionals (wealth managers, financial planners, investment advisors, etc). When one looks past these labels, there are only two primary classifications for licensed investment professionals: investment advisors and securities brokers. Knowing which one you are talking to is critical as it determines the standard of care they should uphold as well as how their affiliations and compensation structure may impact their advice.
Different investment professionals uphold different standards for the advice and recommendations they provide. For example, brokers are held to a suitability standard. In other words, they only need to have a reasonable basis to believe the products they sell are suitable – even if they know they are not necessarily the best choice.
Independent investment advisors uphold a fiduciary standard. This standard of care requires advisors to put the interests of their clients first, act with prudence, and disclose all important facts. The section below provides a simple example to illustrate the difference between standards of care.
A securities broker and an advisor both find S&P 500 index funds would make sense for their clients. The market offers several S&P 500 index funds with varying fees and commissions – all of which perform virtually the same before fees. Under the suitability standard, a broker could sell a S&P 500 index fund with higher fees so he can receiver a larger commission (taken out of the client’s investment). However, as a fiduciary advisor, we must put our clients’ interests first and would recommend a low-fee index fund without commissions.
Some consider compensation structures to be even more important than standards of care. For example, brokers typically receive commissions for selling investment products to clients. These monetary incentives may influence their advice and recommendations.
Conflicts of interest may also exist at the firm level. For example, many large investment firms employ pay-to-play schemes. That is, they make product providers (e.g., mutual fund companies) pay them fees to be included on their platform for distribution to their wealth management clients. This naturally constrains the universe of investments for these firms’ advisors, but it also encourages the firm to favor products from companies who pay them the most fees.
While this issue has been flagged by some major financial publications (e.g., Barron’s and SSRN), the private nature of these agreements makes it difficult for investors to identify, let alone understand, the potential conflicts and their implications.
Complicating matters further is the overlap between brokers and advisors. Most investment advisors are dually registered. That is, they are registered both as advisors and brokers. This ambiguity is a contentious issue within the investment world. Indeed, many question the ability of financial professionals to switch broker/advisor hats without misrepresenting themselves, the products they are selling, or their standards of care.
We view dually registered advisors as wolves in sheep’s clothing. Moreover, the statistics are damning. These dually registered professionals tend to charge higher fees and are subject to more disciplinary actions than advisors or brokers (see The Worst of Both Worlds? Dual-Registered Investment Advisers).
SIMPLICITY
Simplicity is the ultimate sophistication.– Clare Boothe Luce

We find the degree to which clients understand their financial plans and investments is strongly correlated to how much peace of mind they ultimately enjoy. That is why our approach to planning and investments embodies the principles behind Occam’s Razor; we prefer financial plans and strategies that are simpler in nature.
On balance, our approach is more structured than those used by most other advisors. The simplicity and transparency of our approach allow our clients to better understand their financial plans.
Given the volatility of market prices, constant media hype, and complex statistical models many advisors utilize, we are never surprised when investors come to us thinking of markets as nothing but unpredictable squiggly lines. This view of markets is superficial and misguided; there is much structure beneath the surface.
Our expertise allows us to see past the volatility and media noise to distill relevant structure and mechanics – especially where income is concerned. We translate these dynamics into simple language and planning models even the most technically challenged investors can understand and appreciate.
SERVICE
The goal as a company is to have customer service that is not just the best but legendary.– Sam Walton
 Our ultimate goal is to provide clients with peace of mind, knowing we manage their affairs with the care and expertise they deserve. Our independent structure, fiduciary approach, and personalized service are designed to help clients understand their financial decisions and receive advice tailored to their circumstances.
Starting with our initial exploratory meetings, you will feel the benefits of working with an independent firm. We strive to acquire a strong grasp of each prospective client’s financial situation, risk profile, investment experience, and overall goals.
Once we are comfortable with one’s balance of expectations and resources, we take the time to ensure our business model and investment philosophy provide a good fit. In particular, we educate clients on how our firm is structured and our investment philosophy.
This mutual understanding is important to us and our clients. An intimate understanding of each client’s financial profile, feelings about investments, and goals is essential for us to serve as stewards of their wealth. Moreover, we find our clients experience more confidence in their financial well-being and peace of mind when they understand the basic principles underlying our firm and investment philosophy.
TRANSPARENCY
There is no persuasiveness more effectual than the transparency of a single heart, of a sincere life.– Joseph Barber Lightfoot

We believe trust and competence are critical ingredients for stewardship of your wealth. The absence of either can pose unnecessary risks by compromising the quality of the advice you receive (e.g., pay unnecessary taxes or fees).
We also believe in 100% transparency. That is why our website highlights many facets of our business, including our backgrounds, the services we provide, and the fees we charge.
In addition to our website, we file a Disclosure Brochure that documents and discloses all material facts about our firm in plain English. This document is required for all registered investment advisors, and you may access it on the Security and Exchange Commission’s website (https://adviserinfo.sec.gov/firm/brochure/155472).
Learn more about Aaron Brask Capital, review our fees and Client Profiles, or schedule a free 30–60 minute consultation.
The Competition
Watch our video to learn who is a fiduciary and who isn't:
Definitely not or not necessarily fiduciary
1. Scammers & frauds
This could be a licensed professional or someone without any professional license or designation. Their intent is to help themselves at your expense. This reminds me of the Samuel Clemens quote, “The return of my money is more important than the return on my money.”


2. Brokers and agents
These are licensed professionals who make money when they sell you a financial product that pays them a commission. They are held to a suitability standard. That is, they can sell you any product they believe to be reasonably appropriate, even if they know better products or investments are available. In particular, they do not have to uphold a fiduciary standard of care. They are typically focused on transactions and commissions rather than on what investments and financial planning strategies are best for you.
3. Dual registrants
These professionals are licensed as both brokers (see #2) and advisors (see #4). You will have to read the fine print to determine whether their advice and services adhere to a suitability versus fiduciary standard. This is the model most large bank wealth management firms pursue. These professionals are typically well-dressed with polished pitches, but they are potentially dangerous wolves dressed in sheep’s clothing. Moreover, their firms will almost never provide, let alone emphasize, financial planning services.


4. “Reformed” mega-bankers
These are professionals who work for big-bank (a.k.a., wirehouse) wealth management firms and change firms every few years. They may tell their clients about better products and services at each new firm, but they are often focused on securing sign-on bonuses and better compensation packages for themselves. Some of these brokers eventually go out on their own. However, they will generally still work with a broker-dealer firm, just one that is not tied to a big bank.
5. Aggregators
Typically backed by private equity, these advisory firms are focused on growing by acquiring independent firms and streamlining operations. Unfortunately, their growth-oriented business model will often prioritize profits over the financial planning activities and personalized service models that made the acquired boutique firms attractive in the first place.

Definitely fiduciary
6. Independent “pie chart” advisors
These are true fiduciaries who want to do good, but focus solely on portfolios – typically involving a variety of low-cost index funds (e.g., from Vanguard) or some other “secret sauce” investment strategy. Because their services are confined to your investments, their financial plan may be nothing more than a simple pie chart stipulating what is in your portfolio. Despite good intentions, these professionals lack expertise or interest in providing financial planning. This service model can overlook important planning opportunities, often resulting in unnecessary risks and paying significantly more taxes.


7. Independent advisors offering financial planning services
These are typically sharp, entrepreneurial individuals or teams who operate under a fiduciary standard. They often utilize financial planning software to run simulations and make projections. While each of their suggestions and planning maneuvers may be helpful (e.g., for reducing costs or taxes), these interdependent strategies are rarely coordinated and optimized.
8. Independent with “optimized” financial planning
These are fiduciaries who offer planning services that coordinate (mathematically optimize) the decisions across Social Security, pensions, portfolios, Roth conversions, withdrawal strategies, and other planning variables. Please see our Value Proposition and Tax Strategies pages for more information.

Video about different types of financial professionals
- The types of products and services they sell
- What standards of care they must uphold (e.g., fiduciary vs. suitability)
- How incentives around compensation can impact their advice
Professionals from almost any of the above categories may or may not be certified financial planners (CFPs). While I am a proud member of the Financial Planning Association (FPA), I made the conscious decision not to pursue the CFP designation.
My reason for this decision is simple: I believe the CFP organization has started to focus more on marketing for its members and enriching itself (e.g., bloated salaries) than benefiting the public by promoting higher standards for financial planning.
To be sure, I am not the only one with this opinion. The Wall Street Journal wrote a scathing article highlighting how the CFP program markets the high standards of its CFP members, but suspiciously omits red flags associated with these professionals (customer complaints, disciplinary actions, etc.).
It is also worth noting that the CFP Board’s 2023 restructuring created the CFP Board of Standards and made it a 501(c)(6) entity. This effectively carved out this money-making part of the organization and allowed them to legally abandon the mission of serving the general public.
Unfortunately, I regularly encounter clients of CFPs who receive little to no planning advice. Moreover, many of them have purchased financial products from their CFP that represent blatant violations of the fiduciary standard. Until the CFP Board raises its standards for planning expertise and begins monitoring the behavior of its members, I will not pursue the designation.